---
title: "Mortgage valuation in Rotterdam: how to prepare"
description: "Prepare a mortgage valuation in Rotterdam by checking lender acceptance, valuation form, property documents, dates and report use."
url: "https://taxateurrotterdam.pro/en/mortgage-valuation-rotterdam/"
locale: "en"
author: "Taxateur Rotterdam Pro editorial team"
publishedDate: "2026-08-28T00:00:00.000Z"
updatedDate: "2026-09-17T00:00:00.000Z"
categories: "Mortgage and valuation"
tags: "mortgage valuation Rotterdam, NHG, valuation report"
---
# Mortgage valuation in Rotterdam: how to prepare
Prepare a mortgage valuation in Rotterdam by checking lender acceptance, valuation form, property documents, dates and report use.
A mortgage valuation in Rotterdam must fit the lender’s conditions and the property. Check the accepted report form, report review, valuation date and delivery deadline before booking. The report supports a lending decision. It does not decide the mortgage amount on its own.
If a lender is waiting for your file, write its recipient, purpose, accepted report form and valuation date before you request work.
## TL;DR
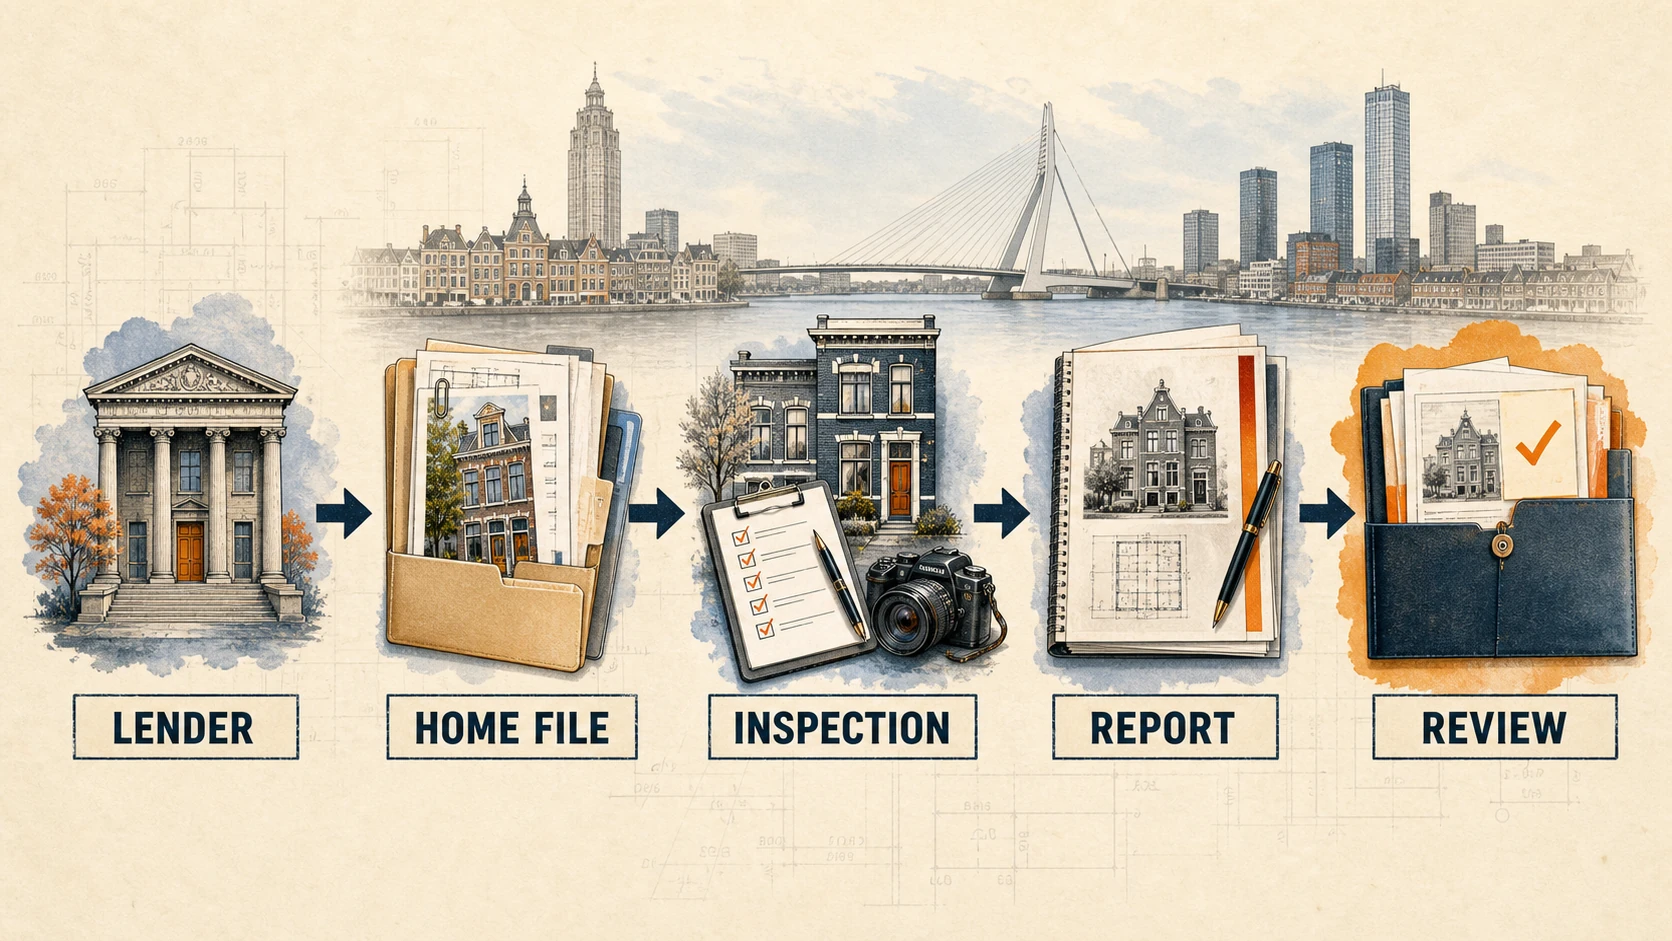
1. Ask the lender or adviser which report it accepts.
2. Confirm the inspection, report review and valuation date.
3. Gather purchase, ownership, leasehold, apartment and renovation documents.
4. Give the valuer a complete and honest property brief.
5. Check the delivered report against the lender’s question.
 Before you compare the report, align your purpose, recipient and evidence with NHG valuation requirements.
For this assignment, keep the relevant property or file facts beside official valuation guidance before you rely on the conclusion.
When your file raises a related question, compare the facts with what is a property valuation report before you choose the report scope.
When your file raises a related question, compare the facts with property valuation costs Rotterdam before you choose the next step.
Before you compare the report, align your purpose, recipient and evidence with NHG valuation requirements.
For this assignment, keep the relevant property or file facts beside official valuation guidance before you rely on the conclusion.
When your file raises a related question, compare the facts with [what is a property valuation report](/en/what-is-a-property-valuation-report/) before you choose the report scope.
When your file raises a related question, compare the facts with [property valuation costs Rotterdam](/en/property-valuation-costs-rotterdam/) before you choose the next step.
## Context that informs this decision
If a section or term is unclear, compare the document structure with valuation report contents.
Compare the written scope beside valuation costs in Rotterdam so a lower amount does not hide a narrower assignment.
If speed is part of the mortgage question, the lender's written conditions still govern the ten property valuer profiles for a fast mortgage valuation; for a new-construction purchase, new-construction valuation documents separate contract, extras and completion evidence.
If a lender is involved, state the recipient and purpose first, then compare those requirements with [a mortgage valuation request in Eindhoven](https://taxatieeindhoven.com/request-mortgage-valuation/) before ordering the Rotterdam report.
The initial file should include home valuation preparation for Rotterdam, while formal valuation versus a value indication separates a provider's suggested indication from a formal report.
A specialist mortgage file may need NWWI report review requirements, NHG physical or hybrid conditions and mortgage valuation requirements in the lender message.
The lender's purpose is tied to why a bank requests a valuation report; refinancing valuation questions identify changes, property purchase valuation steps set the purchase sequence and new-construction valuation and structural inspection separate contract from condition evidence; NHG property valuer selection keeps provider fit separate from an unverified ranking.
Within its mortgage context, NHG residential valuation rules state that a valuation supports the market value used for a mortgage and that physical, model-based and hybrid forms exist.
Borrowing capacity relates to income and the home's value under Dutch rules on maximum mortgage.
For a physical valuation in an NHG context, NHG requirements for a physical valuation report state that the valuer must be independent, the report must be validated by an accepted institute and the report may be no more than six months old counted from the valuation reference date.
Before the appointment, the purpose, recipient and property documents form the starting set for home valuation preparation in Rotterdam.
## Mortgage basics: what the report does
The report records an opinion of the home’s market value for a stated date and purpose. The lender uses that information with income, debts, interest rate, loan conditions and other application details.
A lender decides what it accepts for your file.
Use a lender or mortgage adviser for a personal calculation.
## What the lender may ask you to confirm
Ask these questions before you order the report:
- Is a physical, hybrid or model-based form accepted?
- Is report review through a named institute required?
- Which valuation date applies?
- How recent can the report be?
- Does the lender use its own application form?
- Are there extra conditions for apartments, leasehold, renovation or new construction?
- On which date must the report arrive?
Confirm the current lender and NHG conditions because your product may use different rules.
## Documents for the property file
Collect:
- purchase agreement and sales information;
- ownership, cadastral and leasehold details;
- deed of division and VvE papers for an apartment;
- drawings, permits and information about extensions;
- energy label and energy improvements;
- renovation invoices, plans and completion details;
- foundation or maintenance information you already have.
Mark any missing or uncertain fact. A changed floor area, unfinished extension or planned alteration can affect the assignment. The valuer can then ask a focused question early.
## Forms of mortgage valuation
### Physical valuation
A valuer visits the home, records relevant facts and writes a report. The inspection and documents should match the report’s purpose and the lender’s conditions.
### Model-based valuation
A model estimates value from available property and market data without a physical visit. NHG explains that a loose model value or WOZ statement cannot serve every mortgage purpose. Ask the lender whether it accepts this form for your file.
### Hybrid valuation
A hybrid form combines a model value with a valuer’s assessment under the applicable rules. NHG allows this in defined situations and describes limits for its use. Ask the lender whether your purchase or refinancing case qualifies.
## Five preparation steps
1. **Write the lending question.** Name the home, lender, purpose and valuation date.
2. **Check acceptance.** Ask the lender or adviser about report form, report review and age.
3. **Send the file.** Share documents and explain missing information.
4. **Prepare the visit.** Give access to all relevant rooms and mention completed or planned work.
5. **Review the report.** Check address, rights, dates, purpose, evidence, assumptions and value.
## How value relates to the loan
The loan-to-value ratio, often shortened to LTV, compares the loan with the accepted property value. A higher value can change that ratio, yet the lender still checks income, other debts, product rules and the borrower’s funds for purchase costs.
The report is an input to the decision. It does not promise approval, set an interest rate or replace the lender’s underwriting.
## Common mistakes
- Booking before checking the lender’s accepted report.
- Giving an old valuation date or the wrong recipient.
- Leaving an apartment’s VvE documents until the end.
- Describing planned work as completed work.
- Assuming an online estimate will satisfy a lender.
- Comparing fees without checking report review and delivery.
## FAQ
### Does every mortgage need a physical inspection?
No. The accepted form depends on the lender, product and case. Ask before booking.
### Can a WOZ value replace a mortgage valuation?
Usually it cannot answer every lender’s requirement. NHG explains that a loose WOZ statement or model value does not serve every mortgage purpose. Confirm the current rule with the lender.
### How old may the report be?
The receiving lender sets the condition. NHG’s linked physical-report requirement states six months from the valuation reference date in that context.
### Does the value guarantee the loan?
No. Income, debts, interest rate, product conditions and other checks also affect the lending decision.
### What if the valuation is lower than the purchase price?
Ask the lender or adviser how the difference affects your funds and loan conditions. Do not assume a higher purchase price can be financed without an approved solution.
## Next step
Get the lender’s conditions in writing, then prepare the file and compare providers on the same assignment.