---
title: "NHG Valuation Report in Rotterdam: Physical or Hybrid?"
description: "Compare physical and hybrid NHG valuation reports in Rotterdam, including the 90% context, six-month age condition and lender checks."
url: "https://taxateurrotterdam.pro/en/nhg-valuation-report-rotterdam/"
locale: "en"
author: "Taxateur Rotterdam Pro editorial team"
publishedDate: "2026-09-01T00:00:00.000Z"
updatedDate: "2026-09-17T00:00:00.000Z"
categories: "Mortgage and valuation"
tags: "NHG valuation report Rotterdam, physical valuation, hybrid valuation, mortgage valuation"
---
# NHG Valuation Report in Rotterdam: Physical or Hybrid?
Compare physical and hybrid NHG valuation reports in Rotterdam, including the 90% context, six-month age condition and lender checks.
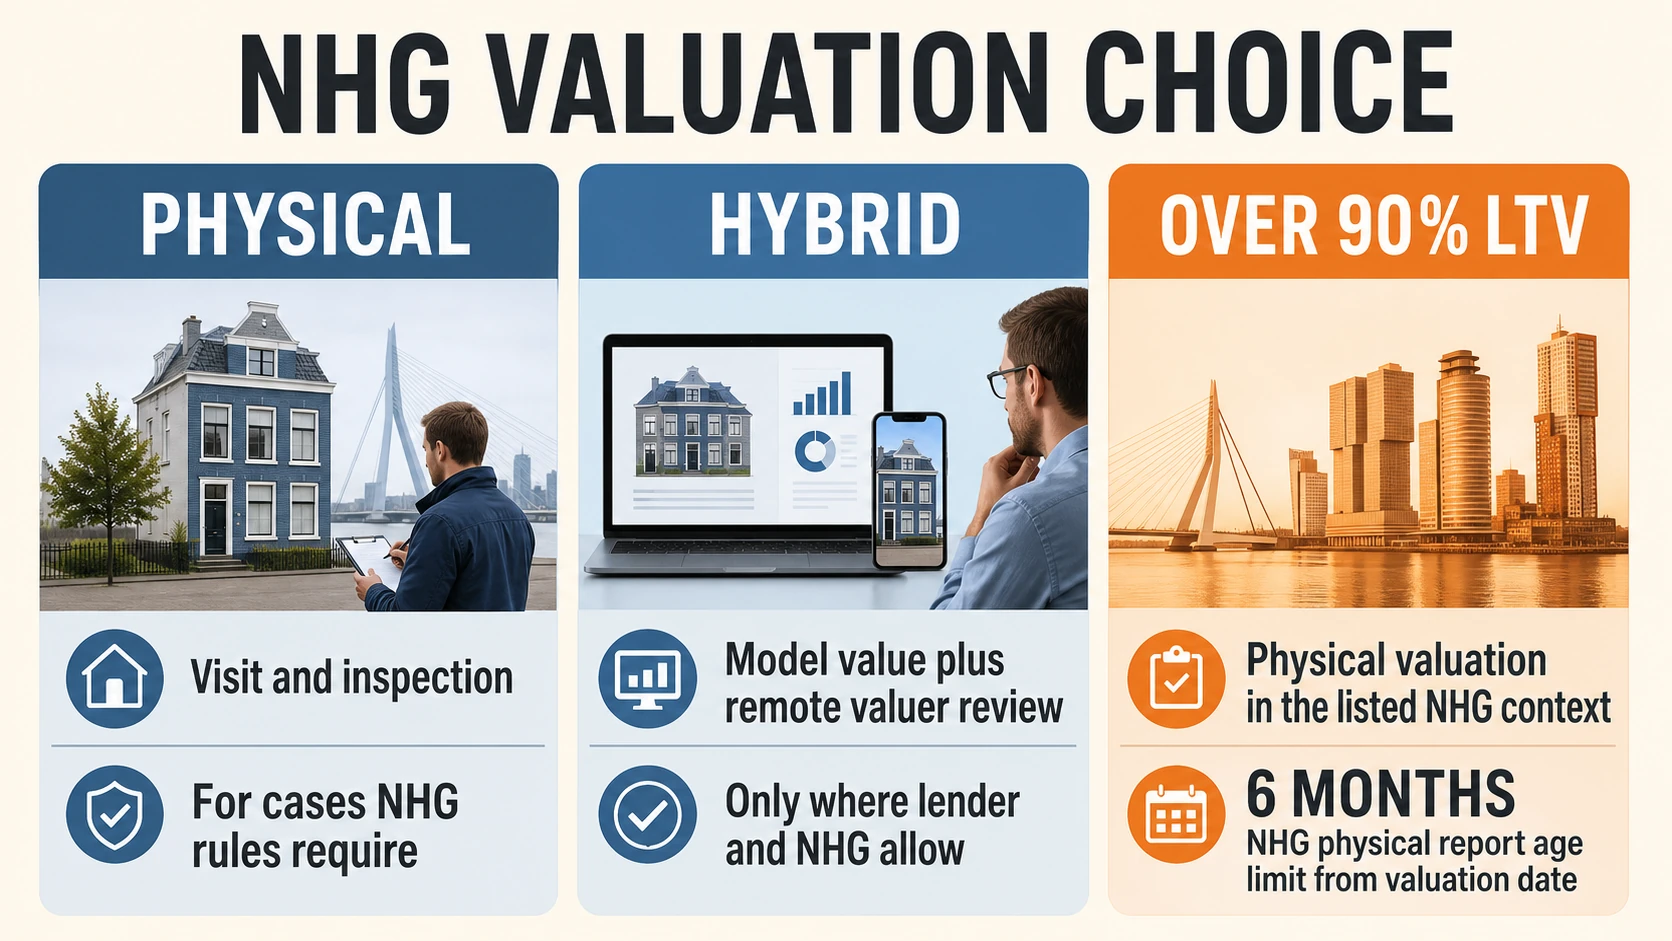
For an NHG valuation report in Rotterdam, the right choice depends on the lender's instructions, the loan percentage, the property situation and the current NHG standards. A physical valuation includes a visit and inspection. A hybrid valuation combines model data with a valuer's remote review when NHG and the lender allow it. Check those conditions before ordering.
If a lender is waiting for your file, write its recipient, purpose, accepted report form and valuation date before you request work.
## TL;DR: which form fits?
Choose a **physical valuation** when the lender or NHG conditions require a visit, when the financing exceeds 90% of market value in the stated NHG context, or when the property situation falls into a listed exception. NHG's physical-report guidance also refers to an independent valuer, accepted report review and a report that is no more than 6 months old from the valuation date in that context.
Choose a **hybrid valuation** only when the lender and NHG allow it for your property and loan situation. It uses model information and a valuer's review from a distance. NHG's current explanation describes the hybrid form up to 90% of market value in its stated context.
Use a **model-only value** for an orientation question only when the recipient accepts it. A model result is not the same as a hybrid valuation or a physical report.
A homeowner plans work that can change the value.
The report may need current and post-improvement information, drawings, permits and a clear improvement overview.
NHG names NWWI as an accepted report review institute in its explanation of valuation.
The report still needs to fit the current lender and NHG conditions.
 Before you compare the report, align your purpose, recipient and evidence with NHG valuation requirements.
For this assignment, keep the relevant property or file facts beside NHG valuation requirements before you rely on the conclusion.
When your file raises a related question, compare the facts with mortgage valuation requirements Netherlands before you choose the report scope.
When your file raises a related question, compare the facts with mortgage valuation Rotterdam before you choose the next step.
Before you compare the report, align your purpose, recipient and evidence with NHG valuation requirements.
For this assignment, keep the relevant property or file facts beside NHG valuation requirements before you rely on the conclusion.
When your file raises a related question, compare the facts with [mortgage valuation requirements Netherlands](/en/mortgage-valuation-requirements-netherlands/) before you choose the report scope.
When your file raises a related question, compare the facts with [mortgage valuation Rotterdam](/en/mortgage-valuation-rotterdam/) before you choose the next step.
## Context that informs this decision
When the lender has not answered these points, mortgage valuation requirements turn the uncertainty into specific questions.
Lender purpose, report form and property evidence meet in mortgage valuation.
NWWI report review requirements concern the separate report-control role.
When preparing an NHG valuation, keep the lender’s criteria separate from [a property valuation in Veldhoven](https://taxatieeindhoven.com/property-valuation-veldhoven/); the recipient’s conditions govern the report.
If the answer is incomplete, send the lender's wording and your question to Taxateur Rotterdam Pro.
Provider fit depends on NHG property valuer selection, while refinancing valuation questions identify changes and new-construction valuation and structural inspection separates related evidence.
NHG requirements for a physical valuation report that the physical-report valuer must be independent, the report must be validated by an accepted institute and the report may be at most 6 months old from the valuation date in that context.
The applicable binding-offer date determines which NHG Conditions and Standards 2026-1 list situations where a physical valuation is required, including financing above 90% of market value, quality or energy improvements, leasehold buyout, certain forced-sale situations with possible residual debt and an auction.
## Who should use this comparison?
This explanation helps:
- buyers arranging an NHG mortgage for a Rotterdam home;
- homeowners refinancing or changing their mortgage product;
- owners planning improvements that can affect the report;
- advisers and applicants who need to distinguish hybrid review from a model-only value.
It does not calculate borrowing capacity or decide whether a lender approves your application.
## At a glance: physical, hybrid and model-only
### Physical valuation
- **Best fit:** a lender or NHG condition that requires a visit and inspection.
- **Evidence:** the valuer visits the home, assesses relevant facts and documents the conclusion.
- **NHG checks:** independence, accepted report review and report age in the stated physical-report context.
- **Special attention:** financing above 90% of market value in the listed NHG context, improvements, leasehold changes, forced-sale situations and auctions.
### Hybrid valuation
- **Best fit:** a case where NHG and the lender accept a model value plus remote valuer review.
- **Evidence:** model data is assessed by a valuer, without the same physical visit as a physical valuation.
- **NHG context:** NHG's current explanation describes use up to 90% of market value in the stated situation.
- **Special attention:** a lender can apply a narrower product policy even when NHG describes the form.
### Model-only value
- **Best fit:** an accepted orientation or product use where no physical or hybrid report is required.
- **Evidence:** a model produces a value indication from data and comparable information.
- **Limit:** there is no physical valuer inspection, and the result may not satisfy the lender's report condition.
The form affects inspection, evidence, timing and acceptance. It does not change the need for a clear property file.
## Physical valuation: when the visit matters
### What happens
A valuer visits the home, considers the property and its evidence, then prepares the report for the stated date and purpose. Tell the valuer about apartment rights, leasehold, extensions, permits, maintenance, foundation information and improvements before the report is finalised.
### Conditions in the NHG physical context
The valuer must also be independent of the purchase, sale, brokerage, building inspection, financing and the parties involved.
A current standard is more reliable than a summary for the individual file.
### Strengths and limits
The physical form gives the valuer an opportunity to see condition, layout and changes that a data model cannot observe directly. It can take more coordination and can expose missing permits, unfinished work or questions that need evidence. A visit does not guarantee a particular value or loan decision.
## Hybrid valuation: when remote review can fit
### What happens
NHG describes a hybrid valuation as model information evaluated and approved remotely by a valuer. The home is assessed through available data rather than the same physical inspection used for a physical report. The valuer still has a professional role in reviewing the result.
### The 90% context
NHG's current explanation describes hybrid use up to 90% of market value in its stated context. If the loan is 100% of market value in that context, a physical valuation is needed. Ask the lender how its product defines the percentage and whether other conditions narrow the choice.
### Strengths and limits
Hybrid work can suit a straightforward property when speed, available data and the lender's product allow it. It is less suitable when a physical fact needs inspection, documents conflict, improvements need a before-and-after view or the NHG standard requires a physical report.
The word hybrid does not mean that every lender accepts the same form. Get written confirmation before paying for the report.
## Decision framework: questions that affect the choice
Use this order:
1. **Recipient:** Which lender or adviser will rely on the report?
2. **Purpose:** Is the file for purchase, refinancing, improvements or another decision?
3. **Percentage:** What loan percentage of market value is being considered?
4. **Property change:** Are there extensions, quality improvements, leasehold changes or unusual rights?
5. **Inspection:** Does the situation require a physical visit?
6. **Date:** How recent must the report be, and which valuation date applies?
7. **report review:** Which institute or report form does the recipient accept?
8. **Documents:** Can the ownership, apartment, permit and renovation facts be supplied?
## Rotterdam scenarios
### Purchase below the 90% context
A buyer has a standard apartment, no planned work and a lender that accepts a hybrid valuation. The buyer still confirms the report form, report review, value date and property documents. A hybrid form can fit only after those checks.
### Purchase with a high loan percentage
A buyer needs financing above 90% of market value in the stated NHG context. The NHG standard points toward a physical valuation. The buyer confirms the lender's current rule and supplies plans, VvE records and known property issues.
### Renovation or energy improvement
### Leasehold change or auction
A leasehold buyout, forced-sale situation or auction can fall within a physical-report condition. The reader should go directly to the current NHG standard and the lender rather than use the hybrid choice by assumption.
## Alternatives and cases where neither choice fits
### A model-only result for orientation
Someone who is only estimating a possible value may use a model result when no recipient needs a formal report. It can help frame a conversation. It cannot answer a lender's physical or validated-report requirement.
### Another accepted report form
A lender may accept another form or a different report review arrangement for a particular product. Ask for the exact name of the accepted report and keep the written answer with the application.
### The property needs a specialist question
When a Rotterdam home has unusual legal rights, construction, foundation or mixed use, the best next step may be a more specific assignment. Describe the fact to the lender and valuer rather than forcing it into a standard hybrid request.
## FAQ
### Is an NHG valuation report always physical?
No. NHG describes physical and hybrid forms, with the lender and current NHG conditions deciding what fits. The loan percentage and property situation can make a physical report necessary.
### Can a hybrid valuation cover 100% of market value?
In the NHG context described by NHG, hybrid use is limited to 90% of market value and a physical valuation is needed at 100%. Confirm the current rule and the lender's product policy for your file.
### How old can a physical NHG report be?
In the cited physical-report context, NHG says the report may be at most 6 months old from the valuation date. The lender can ask for a different or more recent condition, so check before ordering.
### Is NWWI required for an NHG report?
### Does a physical visit guarantee a higher value?
No. A visit gives the valuer direct information about the property and its condition. The conclusion still depends on evidence, purpose, date and professional judgment.
### Can a hybrid report be used after a renovation?
That depends on the improvement, lender and current NHG conditions. If the work needs a current and post-improvement view or the standard requires a physical visit, a hybrid form may not fit.
### Is a model-only value the same as a hybrid valuation?
No. A model-only result has no remote valuer review of the same kind. A hybrid valuation combines model data with review by a valuer under an accepted process.
### Who decides which form my mortgage needs?
The lender decides what it accepts for the product, using its policy and any NHG conditions that apply. Ask the lender or adviser before you instruct a valuer.
## Next step
Write down the lender, purpose, loan percentage, improvements, property rights, required date and proposed report form.
Ask for written confirmation of physical or hybrid acceptance, report review and report age.