Property valuation during divorce in the Netherlands: how to prepare the value question
Prepare a home valuation during divorce by separating market value, ownership, mortgage debt, sale costs and the legal or tax questions around a buyout.
If you are preparing a property valuation during divorce, write down the purpose, recipient and value date before you compare the available evidence. A property valuation during divorce can clarify one part of a difficult decision, but it does not decide the agreement. Separate the market value, ownership share, mortgage balance, sale costs and legal or tax questions before asking for a report. The person who remains in the home may need a buyout calculation, while both partners may need a sale plan or lender confirmation.
TL;DR
The useful order is to separate value, ownership, debt, sale costs and the agreement that the parties still need to make.
When a relationship ends and a home is involved, define the value question separately from ownership, debt and the agreement between the parties.
Before you compare the report, align your purpose, recipient and evidence with Belastingdienst buy-out information.
For this assignment, keep the relevant property or file facts beside Belastingdienst buy-out information before you rely on the conclusion.
When your file raises a related question, compare the facts with property valuation costs Rotterdam before you choose the report scope.
When your file raises a related question, compare the facts with how to choose a reliable property valuer before you choose the next step.
Before you compare the report, align your purpose, recipient and evidence with Belastingdienst buy-out information.
For this assignment, keep the relevant property or file facts beside Belastingdienst buy-out information before you rely on the conclusion.
When your file raises a related question, compare the facts with property valuation costs Rotterdam before you choose the report scope.
When your file raises a related question, compare the facts with how to choose a reliable property valuer before you choose the next step.
Context that informs this decision
When a home is sold after separation, overvalue, residual debt and ownership shares need to be separated before the lender assesses affordability and release of liability.
Before accepting an assignment, compare property valuation costs in Rotterdam with the written scope, delivery conditions and extra-work terms.
Before appointing someone, compare independence, scope and evidence against the tests in reliable property valuer selection.
When the first valuation brief is ready, property valuer profiles for divorce-related valuations in Rotterdam keeps provider fit separate from the settlement itself.
Before discussing value, write down the purpose, date, evidence and assumptions that belong in valuation report contents.
For a buyout, economic value after a divorce is a relevant starting point, but the amount still depends on the rest of the situation.
If you are dividing a home, compare ownership and mortgage decisions with the address evidence in a property valuation in Eersel, keeping the Rotterdam settlement tied to the actual property.
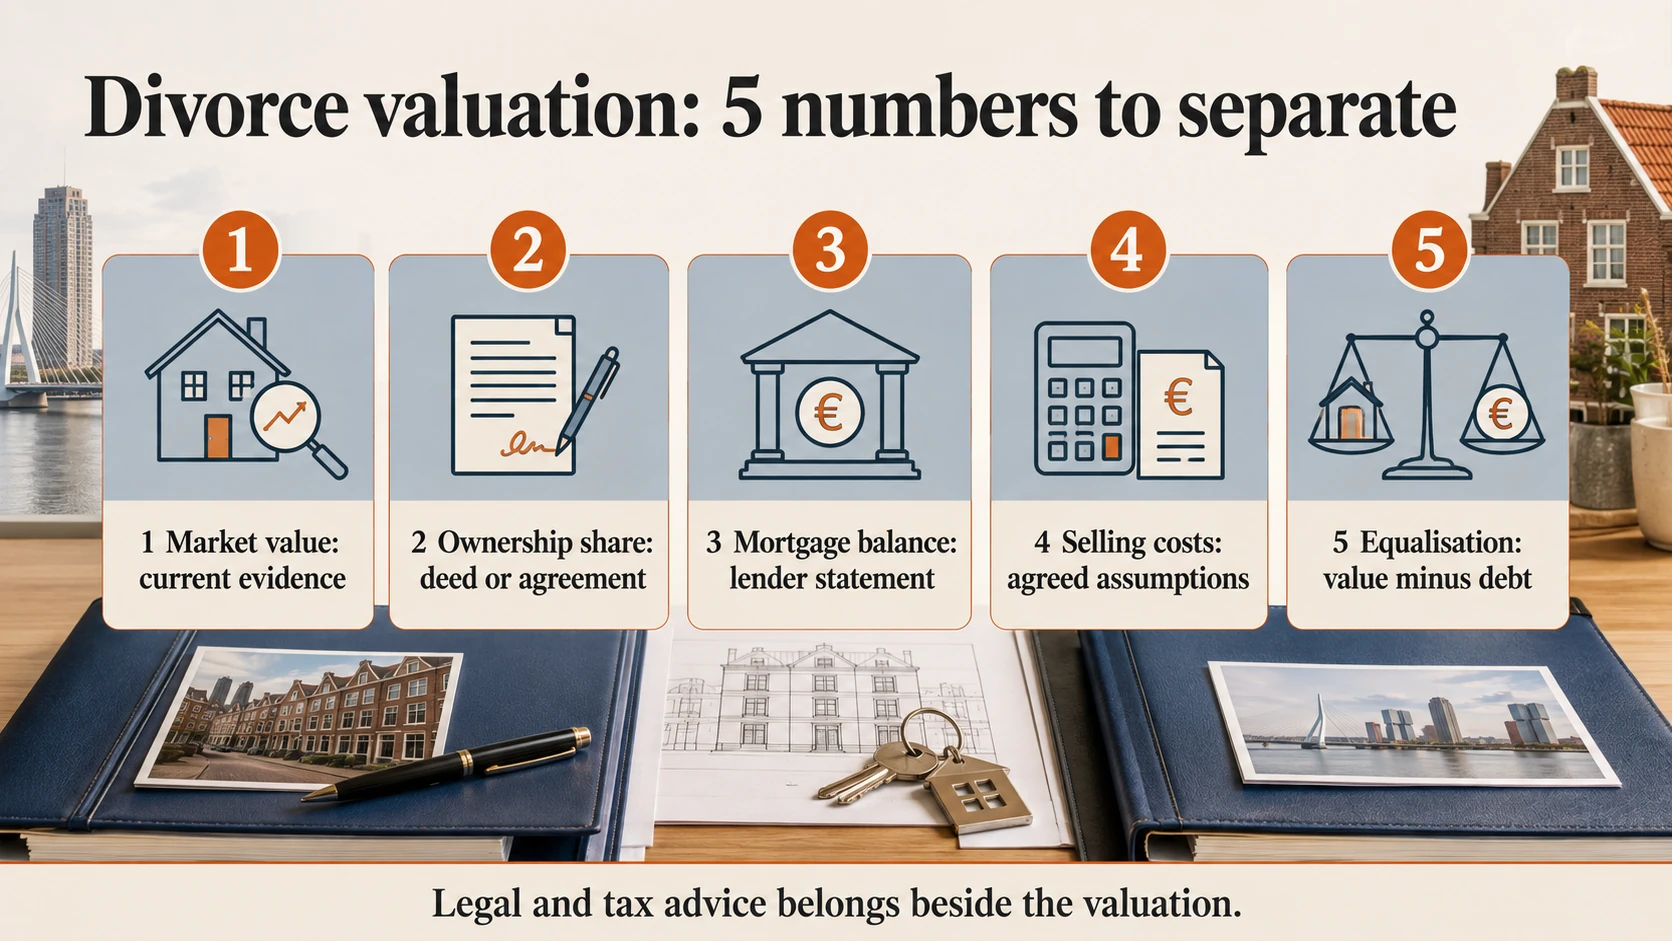
1. Start with the five numbers
Write down:
- Current market value for the stated purpose and date.
- Ownership share from the deed or agreement.
- Mortgage balance and other secured debt from the lender.
- Selling or transfer costs under the assumptions used.
- The amount that still needs legal and tax review.
The visual below keeps these inputs separate. It is a preparation tool, not a settlement calculation.
Compare valuation quotes by scope, date, inspection, report recipient and follow-up, not by a headline fee alone.
Who this explanation helps
- Partners deciding whether to sell the home.
- One partner considering a buyout.
- Advisers who need a clear valuation brief before discussing an agreement.
- Families who need a calm way to separate home, debt and document questions.
It does not replace a lawyer, mediator, lender or tax adviser.
2. Options for the home
Sell the home
The sale price, mortgage repayment, selling costs and ownership agreement determine what remains to divide. The Belastingdienst explains that a sale can result in overvalue or residual debt and that ownership shares matter. A sale decision still needs legal and financial advice for the individual agreement.
One partner buys out the other
The partner who stays may pay for the other partner’s share.
The lender must also confirm whether the remaining partner can carry the debt. A valuation does not release someone from a mortgage by itself.
Temporary co-ownership
Some partners keep ownership for a period while a sale or refinancing is arranged. Put ownership, costs, occupation, maintenance, timing and the end condition in writing with legal help. The valuation date should match the decision being made.
3. What the valuation assignment should say
The brief should name:
- the property and rights being valued;
- the recipient and purpose;
- the valuation date;
- the inspection and documents available;
- known alterations, defects or leasehold conditions;
- the questions that remain uncertain.
Ask whether the value is meant to inform a buyout, a sale, a lender conversation or another purpose. One report may not fit every recipient.
4. Evidence and a second view
A useful file can include the deed, mortgage statement, floor plans, permits, renovation records, relevant VvE papers and information about condition. The specialist should explain which evidence was used and which assumptions remain.
If one partner disputes the result, start by naming the disputed input: date, property fact, comparable, ownership or cost assumption. A second professional may be useful when the question is material, yet two reports do not automatically settle a disagreement. Put the review process in the agreement or obtain legal advice.
5. Sale and mortgage questions
6. Legal and tax boundaries
The valuation supplies evidence for a stated question. A lawyer or mediator handles the agreement, ownership transfer and conflict process. A tax adviser handles personal consequences. The lender decides lending conditions and whether a partner can be removed from the debt.
Keep the public question narrow. Do not upload passports, contracts, bank statements or full mortgage files to a public contact form.
7. Practical communication during a difficult decision
Use one shared list of facts and mark each item as confirmed, disputed or still missing. Keep the conversation about documents and decisions rather than guessing what a value should be. If direct communication is unsafe or unworkable, use the legal or mediation channel chosen by the people involved.
Children, temporary housing and timing can affect the practical plan. They do not change the need to state the valuation purpose and date clearly.
8. The professionals and their roles
- Valuer: examines the property evidence and gives a value conclusion for the assignment.
- Lender: checks affordability, debt and release conditions.
- Lawyer or mediator: handles agreement, ownership and conflict questions.
- Tax adviser: assesses personal tax effects.
- Estate agent: can advise on sale preparation and marketing, which is different from an independent valuation.
A calm preparation plan
- Agree which question the value must answer.
- Obtain the deed, lender balance and relevant property records.
- Record ownership shares and the valuation date.
- Ask the valuer, lender and legal adviser their separate questions.
- Keep the report, assumptions and agreement drafts together.
FAQ
Is the WOZ value enough for a buyout?
It may answer a municipal tax question rather than the current market-value question for a buyout. Ask the lawyer, lender and valuation professional which value basis and date they need.
Does a valuation decide how much one partner receives?
No. It can supply one input. Ownership, debt, costs and the agreement determine what follows.
Can a partner be removed from the mortgage after a buyout?
The lender decides whether the remaining partner qualifies and whether the debt can be changed. A valuation alone does not release a borrower.
Should both partners order separate reports?
That depends on the agreement and whether the first report is accepted. Discuss the review process before ordering another report.
What should I ask Taxateur Rotterdam Pro?
Ask about the valuation purpose, date, evidence and report scope. Contact us with the question only and keep personal documents out of the public form.
List the home purpose, ownership shares, mortgage balance, valuation date and the decision the value will support. Ask a lawyer, tax adviser or lender about the agreement, tax and financing consequences. Contact us with a question about the valuation scope, and do not send passports, contracts, bank details or other personal documents through the public form.
Ask about a divorce valuation question →