Mortgage Valuation Requirements in the Netherlands: Rotterdam Checklist
Use this Rotterdam checklist to confirm the recipient, report form, valuation date, independence, documents and lender acceptance before ordering a mortgage valuation.
Mortgage valuation requirements in the Netherlands start with the lender or other recipient of the report. Before you order a valuation for a Rotterdam home, confirm the accepted form, purpose, valuation date, inspection, report review, independence rules, property documents and delivery deadline. A complete checklist reduces the chance of ordering a report that does not fit the file.
For a lender-facing file, confirm the accepted report form, report review, valuation date and delivery deadline before you book a valuation.
TL;DR: six checks before ordering
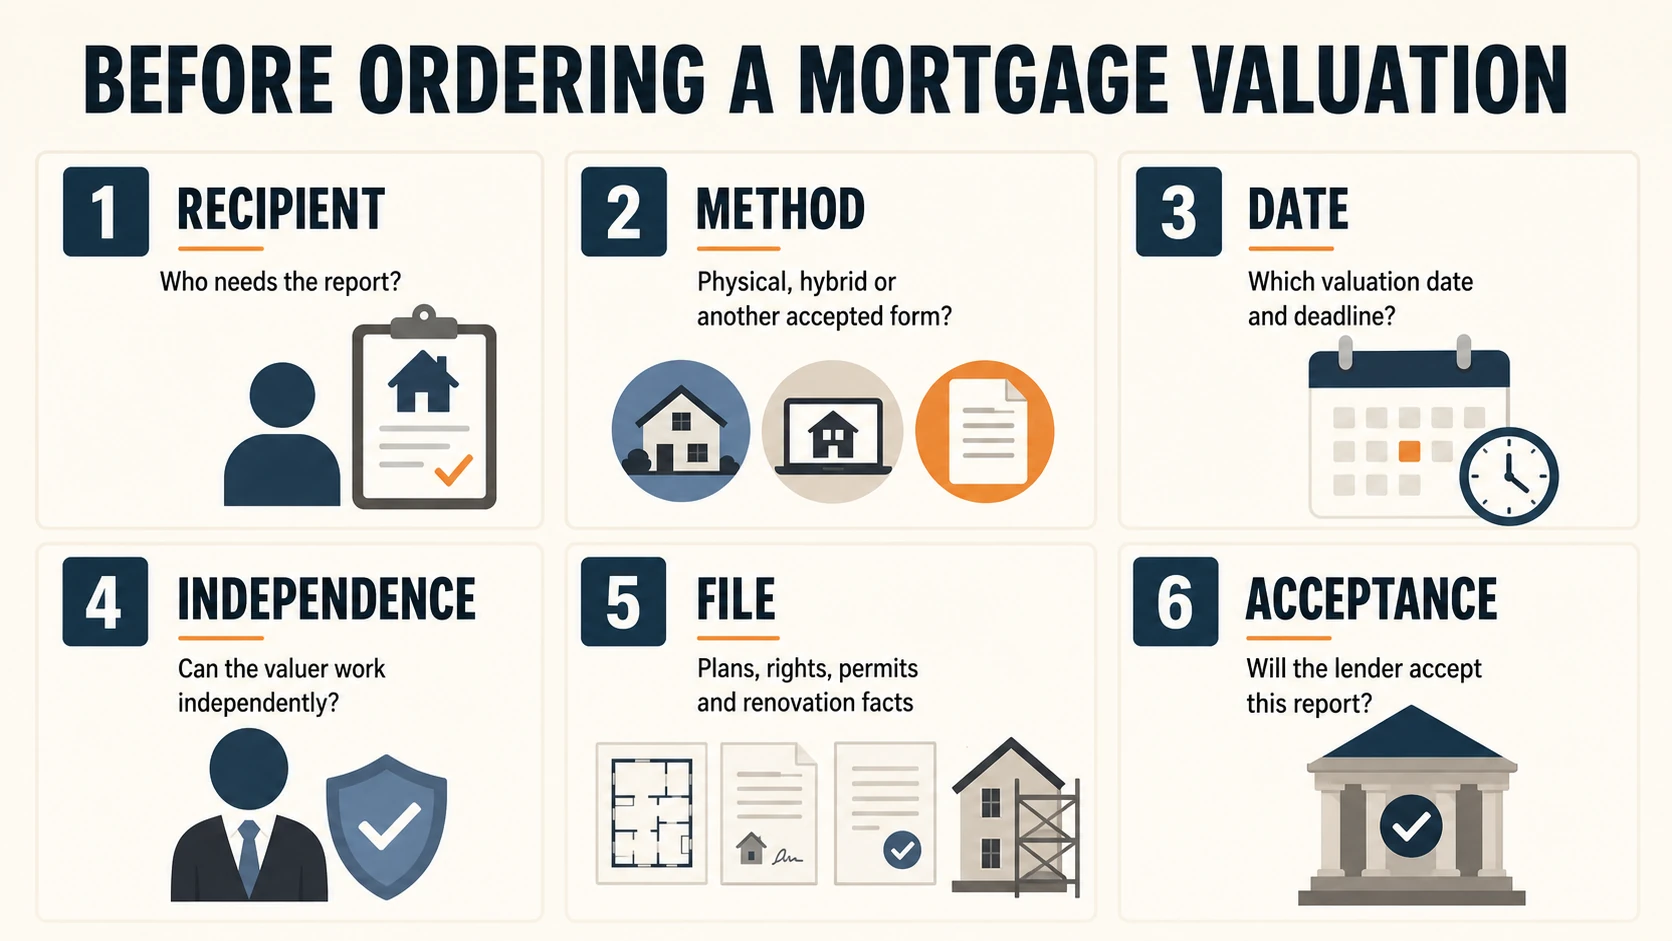
To order a mortgage valuation that fits the file, start with the recipient, confirm the form and date, test independence, prepare the property file and get acceptance in writing.
- Confirm who needs the report.
- Confirm the accepted valuation method.
- Confirm the value date and deadline.
- Confirm independence and the responsible valuer.
- Prepare the property file.
- Confirm lender acceptance before the appointment.
It depends on the lender, product and report form.
Send the six checks to the lender or adviser and ask for one written answer covering form, date, report review, independence, documents and deadline.
Then share the confirmed brief with the valuer.
Before you compare the report, align your purpose, recipient and evidence with official valuation guidance.
For this assignment, keep the relevant property or file facts beside NHG valuation requirements before you rely on the conclusion.
When your file raises a related question, compare the facts with registered property valuer Rotterdam before you choose the report scope.
When your file raises a related question, compare the facts with what is a property valuation report before you choose the next step.
Before you compare the report, align your purpose, recipient and evidence with official valuation guidance.
For this assignment, keep the relevant property or file facts beside NHG valuation requirements before you rely on the conclusion.
When your file raises a related question, compare the facts with registered property valuer Rotterdam before you choose the report scope.
When your file raises a related question, compare the facts with what is a property valuation report before you choose the next step.
Context that informs this decision
Response: The person-level question is separate from report acceptance; registered property valuer checks concern the person, while the recipient sets the report conditions.
The report’s role is defined by valuation report contents, while home valuation preparation in Rotterdam orders the property information.
When the lender names NWWI, the file must meet NWWI report-report review requirements; ask the recipient for a written answer.
If you are preparing a lender-facing file, compare the report, recipient and purpose with Dutch mortgage questions before an offer before fixing the valuation brief.
If the requirements or document list remain unclear, send us the lender’s wording and the unanswered question.
Borrowing capacity involves more than the home’s value under Dutch rules on maximum mortgage.
A lender weighs market value alongside income, debts, interest and product conditions in a mortgage valuation.
Within NHG’s mortgage context, NHG residential valuation rules have different characteristics.
NRVT residential valuation rules and professional rules make independence part of the assignment conversation.
When the lender uses that term, the separate report-control question concerns NWWI report review requirements.
If NHG is involved, the relevant binding-offer date determines which NHG Conditions and Standards apply.
Percentage, improvements and property circumstances can change the accepted form, as reflected in NHG physical or hybrid conditions.
Who should use this checklist?
Use it if you are:
- buying a home in Rotterdam and the lender asks for a valuation;
- refinancing or changing mortgage product;
- planning improvements that may affect the report;
- checking whether a physical, hybrid or another accepted form is suitable;
- helping an applicant turn lender wording into a clear brief.
This information does not calculate borrowing capacity.
What you need before you start
Collect:
- the lender’s written request or the adviser’s exact wording;
- the property address, purchase or refinancing purpose and intended recipient;
- the required valuation date and delivery deadline;
- purchase agreement or current ownership information;
- apartment, leasehold, permit, plan, maintenance and renovation documents that may matter;
- the name of the person or department that can confirm acceptance.
Do not guess the report form from a search result or an older mortgage file. Requirements can differ by lender, product, property and binding-offer date.
Why the recipient comes first
A valuation report is prepared for a stated purpose and date.
The report is one part of a lending file.
The recipient may ask for a physical report, a hybrid valuation, NWWI report review, a named form, a maximum age or a particular delivery channel. That is why an appointment should follow the requirement check. A valuer can help clarify a property question, while the lender decides what it accepts.
Detailed requirements and limits
The report form
Ask whether the lender accepts a physical valuation, a hybrid valuation, a model-based value or another named form.
The lender’s product can use a narrower rule.
The valuation date and age
Ask which value date belongs in the report and how recent the report must be when it arrives. In the cited NHG physical-report context, a report may be at most 6 months old from the valuation date. A lender can ask for a shorter period or another date.
Independence
Ask who performs and signs the work and whether that person has been involved in purchase, sale, brokerage, financing, construction inspection or renovation.
report review
Ask whether NWWI or another institute must validate the report.
report review and professional registration are separate checks.
Property documents
Ask which documents are required for the address. An apartment may need a deed of division, VvE information and planned maintenance. Leasehold may need the contract and payment position. An extension or renovation may need drawings, permits, invoices and current or planned details.
Product and NHG conditions
Step-by-step: define the brief before booking
1. Confirm the recipient
Write down the lender, adviser or other party that will rely on the report. Ask for the exact report name, intended use and delivery channel. Success at this step means you can quote the requirement in one paragraph without using a general phrase such as “for the mortgage”.
2. Confirm the method
Ask whether the lender accepts physical, hybrid or model-based valuation. If a hybrid option is mentioned, ask whether it applies to this property, percentage and product. If the lender uses NWWI wording, ask whether report review is required and who arranges it.
3. Confirm the date
Ask for the valuation date, report deadline and maximum age at delivery. Put all three dates in your notes. If the purchase, refinancing or offer date moves, ask whether the report remains usable.
4. Confirm independence
Ask the valuer to identify the person who will perform and sign the work. Disclose any earlier involvement in the transaction, renovation or financing. If the valuer cannot work independently, tell the lender before the appointment is fixed.
5. Prepare the file
Create one folder with purchase or ownership documents, apartment and leasehold papers, plans, permits, renovation facts, energy information and maintenance or foundation information already available. Add a short note about anything missing or uncertain. Success means the valuer can see the property facts without reconstructing them from scattered messages.
6. Confirm acceptance
Send the proposed report form, responsible valuer, property address and deadline back to the lender or adviser. Ask for a written confirmation before you commit to the appointment or pay a separate report review charge. Keep the reply with the property file.
Scenarios and variations
Purchase of a standard apartment
The buyer has a clear lender request, no planned changes and complete VvE documents. The buyer confirms the form, date, report review and delivery point, then gives the valuer the purchase agreement and apartment file. The physical or hybrid choice follows the lender’s answer.
Refinancing with a new lender
An older report is available, yet the new lender has its own product and report-age conditions. The homeowner asks which parts of the earlier report can be used and which must be repeated. A previous report is evidence for the conversation, not automatic acceptance.
Renovation or energy improvement
The homeowner plans an extension or energy work. The brief identifies current condition, proposed work, plans, permits, budget and expected completion. The lender confirms whether it needs a physical valuation or a report that distinguishes current and post-improvement value.
Leasehold or unusual rights
The home has leasehold terms, a possible buyout or another legal feature. The applicant supplies the relevant contract and asks how the feature should appear in the report. A standard form may need a specific property question.
Common mistakes and what to do
Booking before the lender confirms the form
Problem: The appointment is set for a report the lender does not use. Response: Ask for the accepted form and save the written answer first.
Reusing an old report without checking the date
Problem: The report falls outside the permitted age or uses a previous purpose. Response: Ask the current recipient about date, age and reuse.
Hiding an unfinished or permitted change
Problem: The report file does not show the true current or planned situation. Response: Give the valuer plans, permits and a clear description before the work begins.
Treating registration as acceptance
Problem: A registered person is assumed to meet every lender condition.
Sending documents in separate, unclear messages
Problem: A property fact is missed during review. Response: Use one labelled folder and a short list of missing items.
Ignoring a change in deadline
Problem: A valid report arrives too late for the offer or application. Response: Tell the lender, adviser and valuer when the date changes.
Aftercare: review the delivered report
Before sending the report onward, check:
- address, property description and ownership position;
- report purpose and intended recipient;
- valuation date and report age;
- market value, evidence, assumptions and limitations;
- inspection or method stated correctly;
- report review details when required;
- renovation, apartment, leasehold and permit facts;
- delivery format and signature.
If a fact is wrong, ask the valuer how it will be corrected. If the lender’s question has changed, ask for a new written brief. Keep the original question and any reply together.
Documents and questions for your file
Copy this message to the lender or adviser:
Please confirm the accepted valuation form, required report review, valuation date, maximum report age, independence conditions, property documents and delivery deadline for [property address] and [mortgage purpose].
Then prepare a document list with four headings: ownership, apartment or leasehold, changes to the home and timing. Mark each item as supplied, missing or not applicable.
FAQ
Does every mortgage in the Netherlands need a physical valuation?
No. Lenders may accept physical, hybrid, model-based or another form depending on the product and property. Ask the lender before booking.
What is the most important mortgage valuation requirement?
The accepted report form and intended recipient should be confirmed first. Date, report review, independence and documents follow from that answer.
How recent must the report be?
The recipient sets the age rule. In the cited NHG physical-report context, the report may be at most 6 months old from the valuation date. Confirm the current lender condition.
Is NWWI required for a mortgage valuation?
When is a physical NHG valuation required?
NHG’s current standards describe physical valuation for certain situations, including financing above 90% of market value in the stated context and particular improvements or property situations. Check the current standard and lender policy.
Can I use a valuation from another lender?
Sometimes a lender can accept earlier work, yet report purpose, date, form and report review must fit the new file. Ask before assuming the report can be reused.
What documents should I provide for a Rotterdam apartment?
Start with the purchase or ownership papers, deed of division, VvE information, planned maintenance, leasehold details where relevant, plans, permits and renovation facts. The lender or valuer can narrow the list for the address.
Who decides whether the report is accepted?
The lender or other recipient decides under its current product conditions. The valuer can explain the work and documents, while the recipient confirms acceptance.
Next step
Ask the lender or adviser to confirm the accepted form, validation, valuation date, maximum report age, independence rules and delivery deadline for your property. If one requirement or document is unclear, contact us with the wording you received.
Ask about mortgage valuation requirements →