Valuation when refinancing your mortgage
Find out when a new lender may ask for a valuation when refinancing, what to prepare and how to check report form, date and acceptance in Rotterdam.
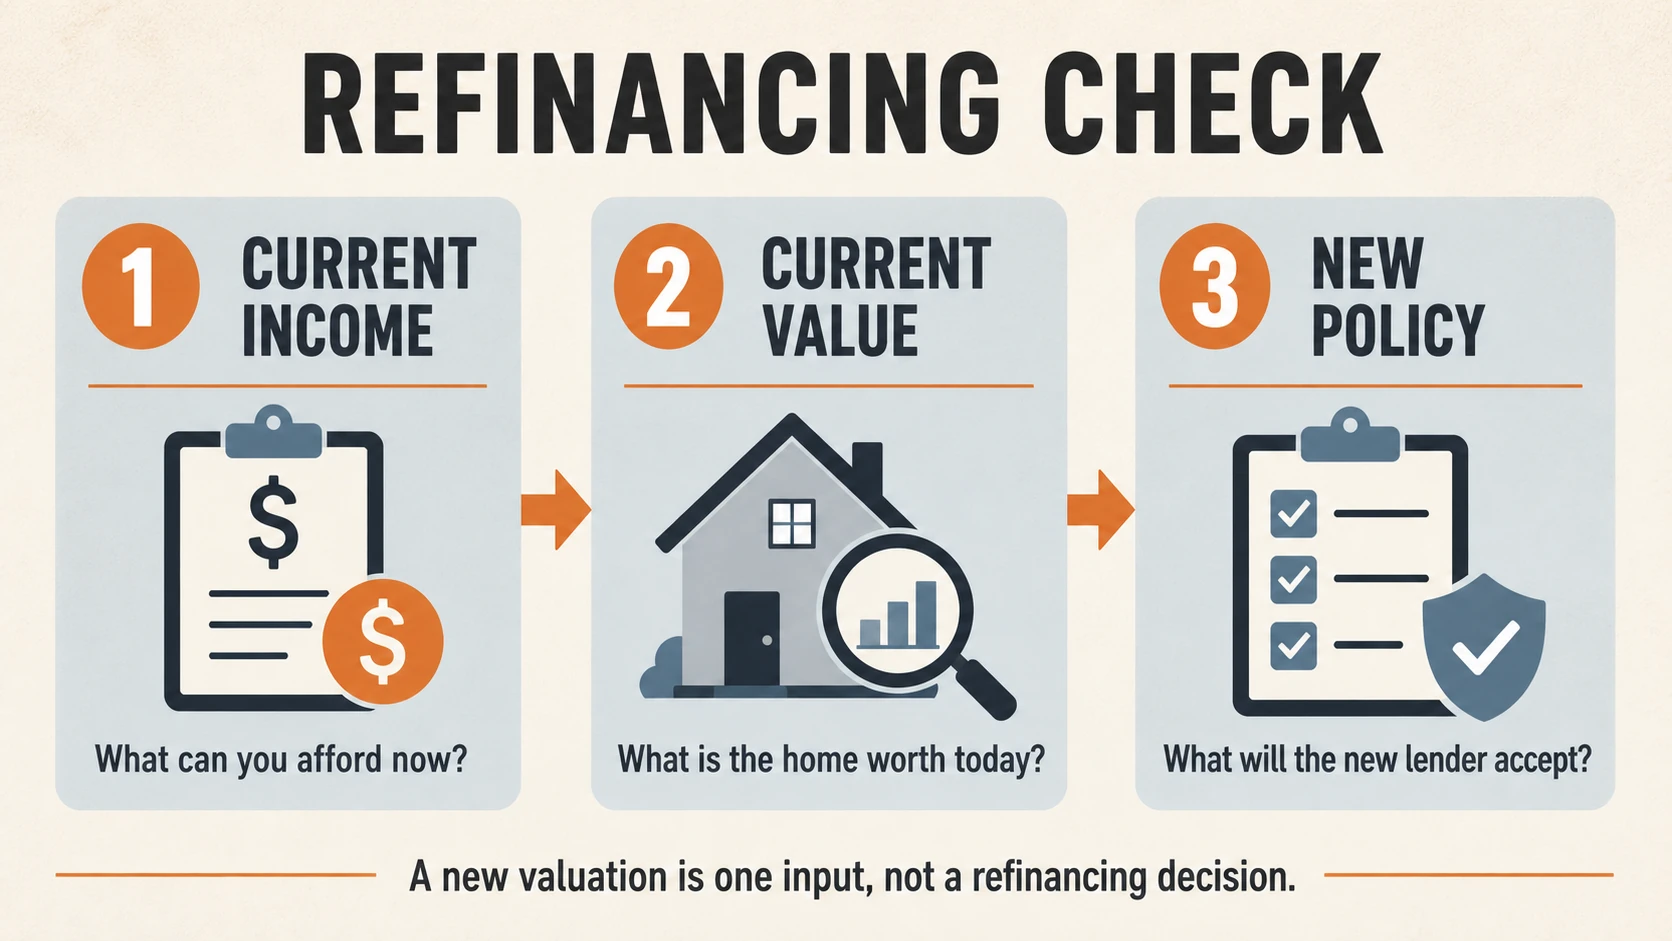
When you refinance a mortgage, a new lender may want to reassess both your current finances and the current value of the home. The AFM explains that a new provider can ask for a valuation report, while a WOZ value may sometimes be accepted as an alternative. The lender’s written instruction decides what you need.
TL;DR
The useful order is to confirm the lender, accepted report form, report review, valuation date and delivery conditions before ordering work.
For a lender-facing file, confirm the accepted report form, report review, valuation date and delivery deadline before you book a valuation.
Before you compare the report, align your purpose, recipient and evidence with official valuation guidance.
For this assignment, keep the relevant property or file facts beside official valuation guidance before you rely on the conclusion.
When your file raises a related question, compare the facts with mortgage valuation requirements Netherlands before you choose the report scope.
When your file raises a related question, compare the facts with mortgage valuation Rotterdam before you choose the next step.
Before you compare the report, align your purpose, recipient and evidence with official valuation guidance.
For this assignment, keep the relevant property or file facts beside official valuation guidance before you rely on the conclusion.
When your file raises a related question, compare the facts with mortgage valuation requirements Netherlands before you choose the report scope.
When your file raises a related question, compare the facts with mortgage valuation Rotterdam before you choose the next step.
Context that informs this decision
mortgage valuation requirements turn these questions into a message for the lender.
mortgage valuation connects lender purpose, report form and property evidence.
If NHG is involved, compare the physical and hybrid NHG context before choosing a form.
If you need help understanding the valuation part, contact us with the wording of the request and the relevant property situation.
When refinancing, keep the lender’s mortgage conditions separate from a property valuation in Nuenen; the Rotterdam file still needs its own address and value date.
Who needs this explanation?
This explanation is useful if you are:
- comparing a new mortgage provider;
- changing a mortgage product or considering an increase;
- unsure whether an older valuation still fits the new application;
- trying to separate the valuation question from interest, advice and notary costs.
The article does not calculate a saving, recommend a lender or decide whether refinancing is suitable for you.
Why might the lender check the value again?
The property is part of the mortgage security. A new provider needs evidence that fits its own file and product. The current value can also affect the relationship between the proposed loan and the home’s value, often described as loan-to-value.
The value can need a fresh look because the purpose has changed, the mortgage amount changes, improvements have been made, the home’s condition is different or the new provider uses a different acceptance policy. A previous report can be useful background without being automatically accepted for a new application.
The value check is only one part of refinancing. The new provider can also review income, debts, employment, the existing loan, requested amount and supporting documents. A favourable value does not guarantee a new mortgage.
The new lender or adviser should confirm the product conditions.
When can a new valuation fit?
Changing mortgage provider
A new provider may ask for current value evidence before it makes an offer or finalises the file. Ask whether it needs a physical valuation, a hybrid form, a WOZ value or another accepted source. Do this before paying for an assignment.
Increasing the mortgage
If you want to borrow more, the lender can need evidence that covers the current property and the proposed loan. Planned work can add questions about the present condition, the intended improvement and the value date. The accepted evidence depends on the product and application.
Changing the mortgage purpose or product
A product change can bring a different report requirement. An existing report may have the wrong purpose, age or recipient. Ask the adviser to state those conditions in writing rather than assuming that the document can be reused.
A change in the home
An extension, conversion, energy improvement, new leasehold arrangement or material repair can change the information the valuer needs. Collect permits, plans, invoices or other relevant documents where they exist. Do not describe planned work as completed work.
A practical preparation sequence
1. Identify the receiving party
Write down the new lender, adviser and product. A report accepted by one lender is not automatically accepted by another.
2. Ask which value source is accepted
Ask whether the file requires a valuation report or whether a WOZ value or another source can be used. Confirm whether the provider wants a physical or hybrid form and whether report review is required.
3. Confirm the purpose and date
State refinancing, increase or product change as the purpose. Ask which valuation date is needed and whether an existing report falls within the permitted age.
4. Describe the home as it is now
List changes since the last report: extensions, layout changes, maintenance, permits, leasehold information and apartment documents. A clear file reduces avoidable questions.
5. Check the wider refinancing file
The valuation does not replace the assessment of income, debts, employment, mortgage balance, advice costs, notary costs or product terms. Ask the adviser which figures and documents are still needed.
6. Order only after confirmation
Use the lender’s wording for the assignment. Keep confirmation of purpose, form, date, report review and recipient with the rest of the file.
Documents and questions to prepare
The exact list belongs to the lender, but these questions help you prepare:
- What is the current mortgage balance and requested new amount?
- Has the property changed since the previous report?
- Are there permits, leasehold documents, apartment rights or owners’ association papers that the file requires?
- Which value date and report age are permitted?
- Is the report used for refinancing only or also for an increase or improvement?
- Does the lender accept a WOZ value or another alternative in this file?
- Does the lender require report review or a specific valuer relationship?
- Which costs belong to the refinancing calculation and which belong to the valuation assignment?
Keep value, cost and savings questions separate
A valuation report answers a property-value question for a stated purpose and date. It does not tell you the total cost of refinancing. Advice, notary, administrative and possible valuation costs can be separate parts of the comparison.
Likewise, a lower interest rate does not by itself prove that refinancing saves money. The result depends on the offer, fees, remaining term, repayment structure and your circumstances. The value report can support one part of the file without answering that financial comparison.
For a Rotterdam home, local property facts may be relevant to the valuation, such as apartment rights, leasehold terms, extensions or the condition of an older building. The address does not remove the need to follow the new provider’s national and product requirements.
What if the current value is lower than expected?
First check that the assignment purpose, property facts and date are correct. If the value is lower, ask the lender or adviser how it affects the proposed loan and which alternatives are available. Do not assume that ordering another report will produce a different conclusion.
If the value is higher, ask how the lender uses it in the loan-to-value calculation. A higher value does not replace income and debt checks, and it does not guarantee the amount you want to borrow.
Common mistakes
- Ordering a new report before the lender confirms the accepted source.
- Treating an old report as reusable without checking purpose and date.
- Describing planned improvements as if they were completed.
- Comparing interest rates without including refinancing costs.
- Assuming a WOZ value is accepted for every product.
- Believing a current value decides the whole application.
- Omitting apartment, leasehold or permit information.
Frequently asked questions
Do I always need a new valuation when refinancing?
No. A new lender may accept a WOZ value or another source in a particular application. Ask the recipient what it accepts before arranging a report.
Can I use the valuation from my original mortgage?
Only if the new lender accepts its purpose, date, form and report review. An older report can provide context without meeting the new file’s conditions.
Does the valuation determine my new interest rate?
It can be one input into a loan-to-value category, depending on the product. The lender’s offer and current terms determine the rate. The report does not set it by itself.
What if I renovated after the last report?
Tell the lender and valuer what changed and provide supporting documents. Planned, incomplete and completed work should be described separately.
Is a WOZ value the same as a valuation report?
No. They are different forms of value evidence. The AFM notes that a WOZ value may sometimes be accepted when refinancing, but the new lender decides whether it works for your file.
Can a higher value increase the mortgage automatically?
No. Income, debts, product rules, documents and the lender’s affordability assessment still apply.
Who should answer my specific refinancing question?
Next step
Ask the new provider for its value-source, purpose, date, form and report review requirements. Then prepare the current property facts and the wider refinancing documents. The mortgage valuation requirements checklist turns these questions into a message you can send to the lender.
Ask the new lender or adviser whether it accepts a valuation report, a WOZ value or another source, and confirm the required date and purpose. Share any improvements or changes to the home. If the request is unclear, contact us with the lender's wording and your question.
Ask about refinancing and valuation →